Georgia business personal property tax generally follows who owned the taxable assets on January 1, even when the business changes hands later that year. Your purchase agreement can divide the expense, but it doesn’t rewrite the county’s tax rules.
Buying a business means taking responsibility for equipment, records, deadlines, and sometimes unresolved tax bills. That January 1 snapshot deserves attention before closing, whether you’re buying a Savannah workshop or taking over a Pooler operation.
Let’s put the ownership change, filing requirements, and tax calculation in order.
Key Takeaways
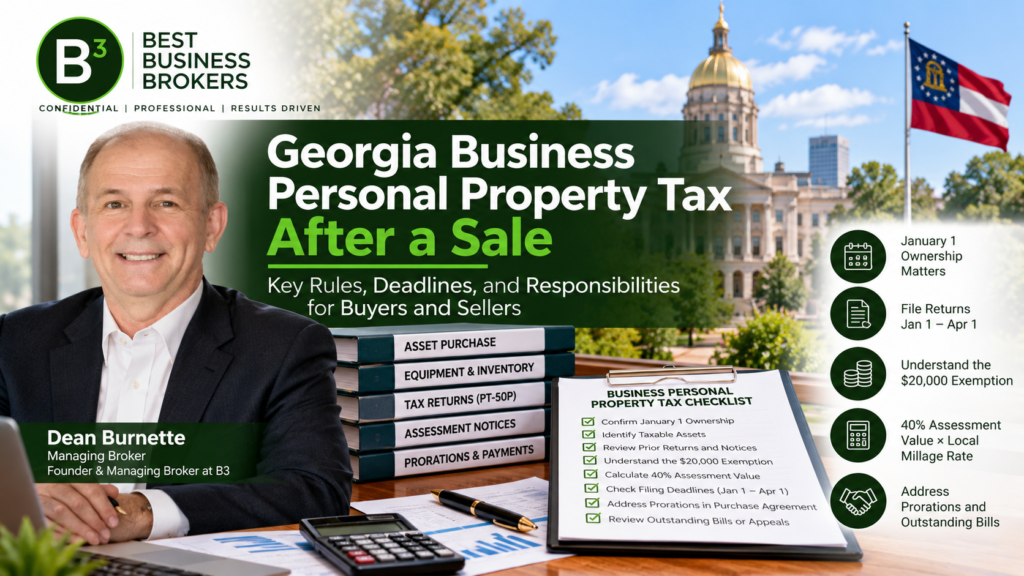
- January 1 ownership and asset location generally control the year’s assessment; closing documents should address tax preparations and outstanding bills.
- The $20,000 exemption is an eligibility threshold based on aggregated fair market value, not a deduction every business receives.
- Returns generally run January 1 through April 1, while an assessment appeal has its own 45-day deadline.
What Changes When the Business Changes Hands?
Asset purchases require a clear handoff
In an asset purchase, the buyer acquires identified equipment, furniture, inventory, and other property. The county needs accurate ownership, location, and mailing information. An asset association schedule should tie each item to its owner, county location, and acquisition records.
The January 1 owner generally remains responsible for that year’s assessment. Buyer and seller can negotiate reimbursement or proration, but their agreement doesn’t change the county’s collection rights.
Our guidance on business acquisition due diligence puts those records into the larger transaction picture. Prior returns, assessment notices, payment receipts, and asset schedules belong in the closing file.
Equity purchases keep the entity in place
Buying an LLC membership interest or corporate stock usually leaves the same legal entity owning the assets. Its property-tax history stays with it.
Think about it: new owners don’t make an old unpaid bill disappear. Review outstanding taxes, pending appeals, and liens before funds change hands.
For either structure, identify who receives notices, who handles an existing appeal, and who pays adjustments after closing. Put those responsibilities in writing while everyone is still at the table.
Which Assets and Forms Belong on the Return?
Tangible personal property includes business machinery, computers, furniture, fixtures, equipment, and taxable inventory. Land and buildings are assessed separately. Goodwill isn’t tangible equipment.
A leased location doesn’t remove the tenant’s equipment from taxation. Leased equipment also needs proper identification so ownership and reporting stay straight.
These are the principal Georgia forms.
| Form | Main purpose |
|---|---|
| Form PT-50P | Business tangible personal property return |
| Form PT-50A | Aircraft personal property return |
| Form PT-50M | Marine personal property return |
| PT-50PF | Freeport exemption application for qualifying inventory |
The Department of Revenue’s forms directory provides the state return materials. Submit property-tax returns to county officials, not the state income-tax office.
For PT-50P Schedule A, depreciation classifications are Group 1, 5 to 7 years; Group 2, 8 to 12 years; Group 3, 13 years or longer; and Group 4, 1 to 4 years.
Keep acquisition dates and original costs available. Fully depreciated equipment on your federal return can still have taxable value for county purposes. The purchase price allocated to equipment also doesn’t automatically become its county-assessed value.
How the $20,000 Exemption Works
Georgia voters approved Referendum A in November 2024. Effective January 1, 2025, it increased the tangible personal property exemption threshold from $7,500 to $20,000. The ACCG legislative report describes the legislation behind that change.
Motor vehicles, trailers, and mobile homes are excluded.
Here’s the distinction that matters, folks: this isn’t a first-$20,000 deduction. Qualifying property is exempt when the taxpayer’s total taxable tangible personal property in the county has a combined value of $20,000 or less.
When that total exceeds $20,000, it doesn’t shelter the first $20,000. Other applicable exemptions can still matter.
The threshold applies to the taxpayer’s countywide property, not separately to each machine, location, or return. Splitting an equipment schedule into several pages doesn’t create additional exemptions.
An ownership change makes accurate reporting especially important. A small operation’s previous exempt status doesn’t establish the buyer’s eligibility if the buyer already owns other taxable equipment in that county.
How Georgia Business Personal Property Tax Is Calculated
Georgia generally assesses taxable property at 40% of fair market value as of January 1. This 40% assessment ratio is applied before the local millage rate, which is charged per $1,000 of assessed value.
For an illustrative calculation, combine $60,000 of machinery, $25,000 of furniture and computers, and $15,000 of taxable inventory. That gives the reported assets a combined value of $100,000.
At an illustrative 30 mills, the calculation is:
$100,000 × 40% = $40,000 assessed value.
$40,000 ÷ $1,000 × 30 = $1,200 annual tax.
The $20,000 threshold wouldn’t reduce that example’s taxable value.
Assessors use three methods where appropriate: the cost approach, the sales comparison approach, and the income approach. Cost considers replacement or reproduction cost less depreciation. Sales comparison uses comparable transactions. Income analysis estimates value through income attributable to property.
For equipment disputes, condition, age, remaining usefulness, and comparable sales can matter. The operating company’s earnings shouldn’t simply be treated as equipment income.
A seller’s old bill is useful history. It isn’t a dependable forecast when assets, exemptions, or values change.
Put Filing and Payment Dates on One Calendar
The annual return window is generally January 1 through April 1. Report assets and ownership as of January 1, even if the transaction closes before the filing deadline.
Plan for annual reporting. Prior-year deemed-return rules or local filing relief don’t excuse an unreported ownership change, acquisition, disposal, or move.
The Freeport exemption is separate and applies to qualifying inventory in jurisdictions that have adopted it. PT-50PF applications follow the same filing window. Late applications can receive partial relief if filed by June 1.
The official ad valorem payment date is December 20. Local governing authorities can move it to December 1 or November 15. Georgia’s property-tax payment guidance also provides a 60-day period after the bill’s postmark before interest accrues. Pay the county tax commissioner or the county’s designated tax collector, where applicable, and follow the instructions on the local bill.
Verify current filing and payment procedures with official county instructions, since dates and procedures can differ by county.
The assessment notice and tax bill serve different purposes. The assessment notice opens the valuation appeal window; waiting for the bill can leave that deadline behind you.
Keep the mailing envelope, notice, submitted return, and proof of filing together. A clear paper trail is worth more than someone’s memory of when an envelope arrived.
Challenging an Assessment After Closing
Start with the 45-day appeal
A written valuation appeal must be postmarked no later than 45 days after the notice of assessment is mailed. Its mailing date starts the clock.
File initially with the county board of tax assessors. Georgia’s PT-311A is the uniform appeal form. Grounds can include value, taxability, uniformity, or denial of an exemption.
Support the appeal with asset records, disposal documentation, condition evidence, or comparable sales. If assessors disagree with a personal property return, they must issue an assessment notice with appeal rights.
Choose the right appeal route
After the assessors’ review, the County Board of Equalization is the usual route for ordinary equipment disputes.
A hearing officer is available for qualifying nonhomestead real property or wireless personal property exceeding $500,000. That option doesn’t cover every business equipment account.
Statutory arbitration is another route and generally produces a binding valuation decision. These are alternative procedures, not mandatory steps in one ladder.
The state’s assessment and refund guidance also addresses taxes erroneously or illegally assessed and collected. Refund claims must begin within three years of payment. That remedy doesn’t automatically reopen a missed valuation appeal.
Keep Other Transaction Taxes Separate
Real estate and lease obligations
A business for sale may include its building, or the buyer may remain a tenant. When comparing businesses for sale, separate the operating assets, commercial real estate, and lease obligations.
Commercial real estate for sale has its own assessment considerations. Our explanation of property tax reassessment after purchase addresses that side of the deal.
A homestead exemption applies to an eligible residence, not a business equipment account. For commercial real estate for lease, distinguish landlord tax pass-throughs from taxes on your own equipment. CRE ownership costs and tenant equipment taxes deserve separate budget lines.
Vehicles, financing, and sales-tax clearance
For vehicles, GA treatment depends on when they were purchased and titled. Most vehicles purchased on or after March 1, 2013, and titled in Georgia fall under the one-time Title Ad Valorem Tax system instead of annual ad valorem taxation.
A long-term note secured by real estate can also trigger intangible recording tax: $1.50 for each $500, or fraction thereof, of the note’s face amount.
Neither charge replaces business personal property tax.
Unpaid sales or withholding taxes raise separate successor-liability concerns. Our Georgia sales tax clearance checklist addresses that closing issue. A private agreement assigning taxes to the seller doesn’t erase the state’s claim, and state tax clearance doesn’t substitute for resolving county property taxes.
Frequently Asked Questions
Does selling during the year remove the seller’s filing responsibility?
A sale after January 1 doesn’t erase the January 1 owner’s responsibilities for that tax year. The closing agreement should identify who prepares the return and how the parties divide the expense.
Does a Georgia business personal property tax return still matter below $20,000?
Yes. The county needs accurate information to establish eligibility and ownership. A buyer shouldn’t assume the seller’s exemption or filing treatment transfers automatically.
What happens if the 45-day appeal deadline passes?
You generally lose the ordinary assessment appeal for that notice. A later refund request has separate legal requirements and isn’t a replacement for a timely disagreement over value.
Give the Next Owner a Clean Tax Handoff
An ownership change goes more smoothly when the asset list, county account, and closing agreement tell the same story. Establish January 1 ownership, document payment responsibilities, and keep the appeal deadline in view.
At B3 Brokers, we help buyers and sellers work through business and commercial real estate transactions with their goals in focus. Bring property-tax records into the conversation early so both sides can move toward closing with a clear understanding of what comes next.
We are Members of the Georgia Association of Business Brokers and Realtors, Commercial Alliance, Georgia Association of Realtors, and National Association of Realtors