Your business runs well day in and day out. The back office holds scattered financial paperwork across folders, inboxes, and desktop spreadsheets. This disorganization can slow decision making and obscure current performance. Correcting it now reduces risk and speeds the sale process.
Selling a Georgia business often starts with buyer-ready financial documents to sell a business Georgia owners need. These documents prevent overvaluation and set realistic expectations for both buyers and lenders. Focusing on this foundation reduces risk before due diligence begins.
Buyers and lenders want concrete proof, not optimistic promises about future growth. This practical checklist helps owners in Georgia and South Carolina organize what matters before due diligence begins. If you want a smooth hand-off, getting your records straight now is the best place to start.
Key Takeaways
- Gather three years of federal and state tax returns alongside current trailing twelve-month statements.
- Reconcile profit and loss statements and balance sheets to show authentic operational cash flow.
- Document owner add-backs with clear receipts and invoices to justify your asking price.
- Clear outstanding debt schedules, liens, and payroll obligations before buyers inspect the books.
Financial Documents to Sell a Business Georgia: What Buyers Expect First
Every buyer due diligence list varies by business size and transaction structure. The core records to prepare include tax returns and profit and loss statements. They also cover balance sheets, cash flow records, and aging reports for financial documents to sell a business Georgia. Clean records help buyers and lenders see the real cash flow without wading through guesswork.
As you prepare, review the broader how to sell my business in Georgia guide. It explains the complete transaction timeline. B3 Brokers helps sellers prepare these records confidentially. They ensure you keep operations running while building a defensible file.
Tax Returns: The Starting Point for Every Serious Buyer
Serious buyers and lenders ask for federal and Georgia business tax returns for at least three years. Personal returns may be required for financing. Under IRS record retention guidance, keep supporting tax documents for at least three years after filing. Buyers compare these returns to bank deposits and financial statements to confirm revenue. Check state registrations through the Georgia tax registration portal to ensure everything matches. Review the financial documents to sell a business Georgia along with your tax returns. Reconcile your returns with internal financial statements before listing to avoid minor discrepancies triggering red flags.
Profit and Loss Statements: Showing How the Business Actually Earns
Profit and loss statements show how your business earns money over time through steady operations. Buyers look for annual P&L statements spanning three years, plus monthly or trailing twelve-month figures for the current operating year. They want to spot gross margin trends, seasonal fluctuations, and unusual one-time revenue or expenses. A good preparation rule is to write down explanations for large financial swings before a buyer asks. B3 Brokers can help frame these numbers honestly so your financial story makes sense to an outside buyer.
Balance Sheet: The Snapshot Buyers Use to Spot Hidden Problems
A balance sheet provides a clear snapshot of your assets, liabilities, and equity on a specific date. Review accounts receivable, inventory values, fixed assets, equipment leases, and vendor obligations carefully. Write off inventory with no real value and reconcile old receivables before buyers inspect the business. Buyers and lenders frequently inspect public records like UCC filings to verify existing equipment liens or collateral claims. Catching these items early prevents painful delays later in the closing process.
Cash Flow: Proving the Business Can Pay Its Bills and a New Owner
Cash flow records prove whether your business can pay its bills, service debt, and support a new owner’s salary. Lenders look closely at debt service coverage and working capital requirements during underwriting. Gather twelve months of bank statements and be ready to explain large deposits or unexpected wire transfers. Michael Gay, a broker with decades of commercial banking experience in Middle Georgia, often reminds sellers that lenders want to see predictable, recurring cash flow that covers the new loan note with room to spare.
Accounts Receivable and Accounts Payable: Clean Up Before Buyers Look
Aging reports for accounts receivable and accounts payable show who owes your business money and what bills you still need to pay. Collect old receivables, write off bad debt, and list unpaid vendor bills before marketing the company. Buyers often request a working capital adjustment based on your AR and AP levels at closing. Keeping these ledgers current ensures due diligence does not stall over uncollected invoices or forgotten supplier balances.
Payroll Records: Employees, Contractors, and Compliance
Payroll registers and tax filings show the true labor cost of running your daily operations. According to the tax document retention guide from the U.S. Chamber of Commerce, payroll tax records should be kept for at least four years. Buyers examine key employee retention, wage rates, and whether owner compensation aligns with market rates. Fixing worker classification issues or unpaid payroll liabilities before a buyer reviews the records protects the deal from collapsing over compliance failures.
Inventory: Value It Honestly and Document the Count
Inventory ties up real working capital, making accurate valuation essential for any transaction. Prepare a current inventory list, document your valuation method, and run a complete physical count. Separate active stock from obsolete or slow-moving items that no longer hold market value. Documenting your counting process ensures your inventory figures match the balance sheet and tax returns without causing friction during buyer inspections.
Debt and Liens: Know What Must Be Paid or Released at Closing
A complete debt schedule lists all business loans, lines of credit, equipment leases, commercial mortgages, and seller notes. Buyers and lenders need to know exactly what must be paid off, released, or assumed at closing. Request current payoff letters and lender consents early in the process. Uncovering unexpected liens or judgments gives you time to build a resolution plan, whereas discovering them late in the transaction can kill a deal overnight.
Documented Add-Backs: The Reality of Owner Perks and One-Time Expenses
Add-backs adjust your net income to reflect the true cash flow of the business under a new owner. As SDE vs EBITDA explanations highlight, seller’s discretionary earnings add back the owner’s full salary and benefits to show what a full-time operator would earn. Common supportable add-backs include one-time legal fees, owner health insurance, and personal vehicle expenses run through the company. Every add-back must tie directly to an invoice, receipt, or tax record to survive buyer scrutiny.
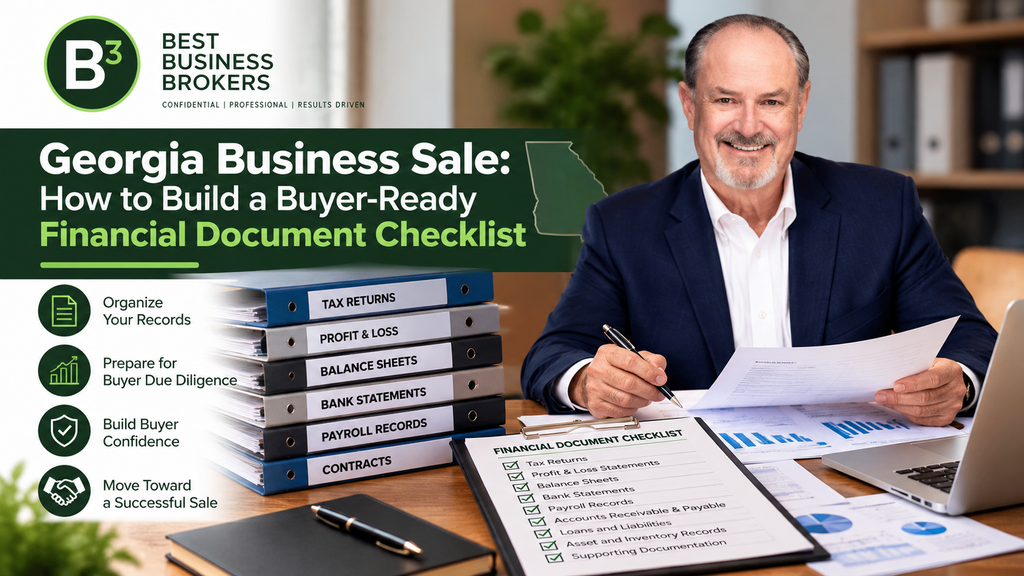
Your Practical Financial Document Checklist: Document, Purpose, Preparation Tip
Use this working checklist to organize your records before speaking with prospective buyers or lenders. When preparing a small business sale readiness strategy, having these items sorted keeps due diligence moving forward smoothly.
| Document | Purpose | Preparation Tip |
|---|---|---|
| Tax Returns | Verify reported revenue against IRS filings | Reconcile federal and state returns with internal P&L sheets |
| Profit and Loss | Show multi-year operational earnings and gross margins | Explain seasonal swings and revenue anomalies in writing |
| Balance Sheet | Detail company assets, liabilities, and equity | Write off dead inventory and reconcile old receivables |
| Cash Flow Statements | Prove ability to service debt and fund operations | Gather twelve months of consecutive bank statements |
| AR and AP Aging | Track customer debts and unpaid bills | Collect overdue invoices and clear vendor backlogs |
| Payroll Records | Validate labor costs and tax compliance | Verify employee classifications and wage documentation |
| Inventory Counts | Establish current physical stock and valuation | Complete a physical count and segregate obsolete items |
| Debt Schedules | Outline existing loans, leases, and financing notes | Request written payoff statements and lender consents |
| Add-Back Documentation | Justify discretionary expenses and owner perks | Attach receipts or invoices to every adjustment |
Frequently Asked Questions
How many years of financial documents do buyers typically request?
Most buyers and commercial lenders request at least three years of historical tax returns and profit and loss statements. This time frame allows them to spot multi-year revenue trends, margin stability, and recurring operating patterns. Providing trailing twelve-month figures alongside those annual reports gives a clear picture of current business health.
Can I prepare financial documents myself or do I need a CVA?
While you can gather initial bank statements and internal ledgers yourself, working with a certified public accountant ensures your financial statements comply with standard accounting practices. A CVA helps reconcile tax returns with balance sheets and models tax consequences for the transaction. Professional oversight prevents errors that could slow down buyer due diligence.
What happens if my financial records have minor discrepancies?
Minor discrepancies between internal P&L sheets and tax returns happen, but you must document and explain them before a buyer discovers them. Transparency builds trust, whereas unexplained variances make buyers suspicious of broader accounting accuracy. Your broker and CVA can help frame these explanations professionally.
Are personal expenses run through the business considered valid add-backs?
Yes, personal expenses like a company vehicle or owner insurance are standard add-backs if you can prove they were funded by the business. You must attach clear receipts, credit card statements, or invoices to every claimed adjustment. Unsupported add-backs are routinely rejected by buyers and lender underwriters.
How do lenders evaluate cash flow during a business acquisition?
Lenders evaluate cash flow to ensure the business generates enough income to cover operating expenses, working capital, and new loan payments. They calculate debt service coverage ratios using adjusted historical earnings and add-backs. Having clean, reconciled cash flow statements makes it much easier for a lender to approve buyer financing.
Next Steps: Request a Seller Consultation with B3 Brokers
Getting your financial paperwork organized is much easier when you have experienced guidance by your side. You can review our Georgia business exit readiness insights to evaluate your timeline. Whether you operate in Savannah, Macon, Atlanta, or Charleston, B3 Brokers helps business owners organize financial documents, understand buyer expectations, and manage transitions with absolute confidentiality. Contact our team to request a seller consultation and start preparing your business today.
Conclusion
Building a buyer-ready financial document checklist turns a stressful transition into an organized, manageable process. Perfect accounting is never the goal, but honest and structured records are essential for keeping buyers and lenders engaged. Start early, work alongside your broker, CVA, and attorney, and address potential questions before due diligence begins. B3 Brokers remains a confidential local resource for sellers across Georgia and South Carolina. Proper preparation protects your hard work and sets the stage for a confident hand-off.
We are Members of the Georgia Association of Business Brokers and Realtors, Commercial Alliance, Georgia Association of Realtors, and National Association of Realtors